

What are health insurance premiums?
With around 7.4 million treatments waiting on NHS lists in England alone (NHS England, August 2026), private health insurance might be an option you’re considering. But if you’ve never had health insurance before, it’s not always clear what you get for your money. Here, we look at health insurance premiums, what they cover and how they work so that you can decide if private medical insurance (PMI) might be right for you.


Richard Eagling is the Senior Editor at myTribe, with 25+ years in personal finance journalism and a CII Certificate in Financial Services. Previously at Moneyfacts and NerdWallet UK, his work has featured in The Guardian, BBC and The Telegraph.
Full BioWhat is a premium in health insurance?
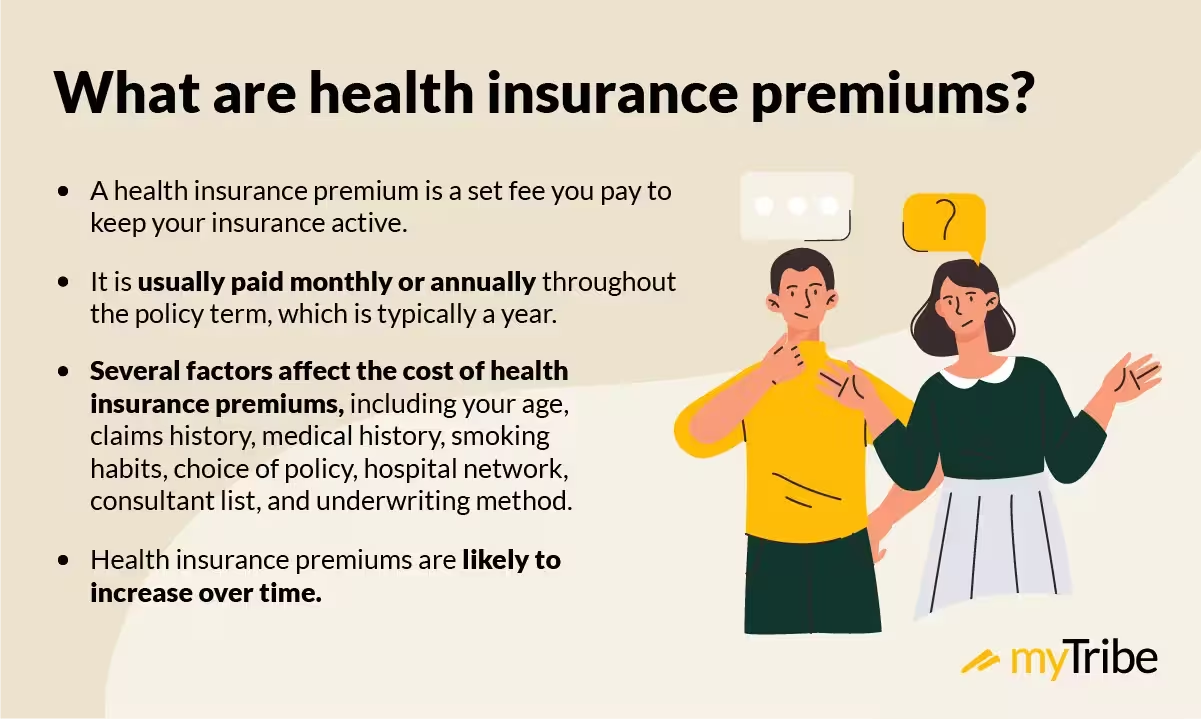
An insurance premium is a fixed amount of money you pay to keep your policy active. Premiums apply to all insurance products, including your car and home cover.
If you take out private health insurance, you’ll pay a monthly or annual premium for the length of the policy term (usually one year).
You can renew your policy with your current provider at the end of the term or look for a new plan elsewhere. Either way, you’ll need to keep paying premiums if you want to continue with private health insurance.
Related guides:
How much does private health insurance cost per month?
Our own research in March 2026 found the average premium for a new private health insurance policy for one adult was £82.53 per month (£990.36 per year).
While that figure is the average across a range of age groups, the premium you pay could look very different depending on your own circumstances. With that in mind, if you’re considering PMI and are concerned about cost, don’t assume that a policy is out of reach simply based on the average.
The average prices from our research are for new policies, typically with a significant no-claims discount applied (as most providers start you off high up their discount levels). If you claim on your policy and get older (we all do), your renewal premiums will likely be higher than our research averages.
Can I pay health insurance premiums annually?
Most premiums are paid monthly, but you should be able to pay for your policy annually – just speak to your provider if this is something you’d like to do.
What affects the cost of health insurance premiums?
Insurance is fundamentally about risk and how likely it is that you’ll make a claim. The probability of you making a claim is then reflected in your premium (the higher the chances, the higher your premium is likely to be).
To calculate the risk, insurers will consider multiple factors, including:
1. Your age
As a rule, health insurance premiums increase as we age because we become more vulnerable to illness and injury.
When we looked at quotes from seven leading insurers, we found that premiums rose at every age and climbed fastest after 60:
*The health insurance prices above are the averages of hundreds of quotes for new policies; if you claim on your policy, your renewal premiums will likely be higher than those listed above. See the next section for more.
Your claims history
If you’ve made a number of claims in recent years, you can expect to pay more compared to someone who hasn’t. When you claim, assuming you don’t have a protected no-claims discount, you’ll drop down your insurer’s no-claims discount levels, reducing the discount you receive on your policy.
You can read more about how claims affect no-claims discounts here.
Medical history
If you’ve suffered from illnesses in the past, your insurer will usually exclude those conditions through your underwriting rather than charge you more for them, so it won’t cover you for that specific condition.
You may still pay a little more than someone in perfect health, because you won’t qualify for the 10% to 15% good-health discounts some insurers offer.
Smoking, vaping and nicotine replacement
Smoking can increase your premium, either through a smoker loading or because you lose a good-health discount, and most insurers will ask whether you smoke before you take out a policy. Some also count vaping and nicotine replacement products such as patches and gum, while others do not count vaping at all.
While vaping and other nicotine replacement products are largely seen as less harmful than smoking, the long-term effects are still relatively unknown, so some insurers treat them in the same way as cigarettes. Our guide to health insurance for smokers shows how each insurer handles them.
Choice of policy
Health insurance plans vary depending on the provider but in most cases, you’ll be able to choose from different levels of cover, for example, from a basic, mid-tier or comprehensive policy. These varying plans typically determine the type of treatment you can access.
Some insurers will also let you add extra features for a fee (such as alternative or complementary treatments).

See what your health insurance would cost
Compare quotes from the UK's leading insurers for your age, your health and the cover you choose.
Rated Excellent

on
How do my policy choices affect health insurance premiums?
As you’d expect, the more treatments and features your policy includes, the more you can expect to pay. But as well as this, your policy is shaped by logistical elements, such as where you’re treated and by who. The way your policy is written is also hugely important in calculating your health insurance premium. Considerations include:
Hospital network
Health insurers work with a network of hospitals. If you need treatment, you’ll be able to choose which of these hospitals you go to. Generally, the wider the network, the more you can expect to pay (as it means greater choice).
However, hospital location also needs to be considered. If your chosen hospital network is in an area with high running costs, your policy will likely be more expensive.
Consultant list
Most health insurance providers will give you some sort of choice over who to see about your condition.
If you choose a policy with an unrestricted list of consultants, it means you can decide who to see. Each insurer will have a maximum they are willing to pay for each type of treatment and consultation, so while you have unrestricted access, bear in mind if you choose a world-renowned surgeon who charges a lot more than their peers, your insurer may not cover the whole cost.
Unrestricted consultant lists typically mean higher costs: in our 2026 research, choosing a guided list instead cut premiums by around 16% on average, so choice comes at a cost.
The alternative is a restricted or guided consultant list. This means you can choose from a list of consultants your health insurer provides. If you opt for a guided list, your provider will ensure that the consultants included are specialists in the area you need treatment, but you won’t have as much freedom over who is treating you.
An aspect of guided vs. unrestricted consultant access often overlooked is waiting times. As the private sector gets busier, consultants on the guided lists of insurers are likely to get booked up faster than those who aren’t. So, there’s a possibility that by opting for a guided list, your treatment may be slower compared to someone with unrestricted access.
Underwriting method
Underwriting describes the way insurers calculate the probability of you making a claim. Your policy can be underwritten in one of two ways:
Moratorium underwriting
When you take out a policy, you’ll only need to answer basic questions and your insurer won’t ask about any health conditions.
Moratorium policies work on the basis that any pre-existing condition is excluded (usually any illness you’ve had symptoms of, or treatment or advice for, in the five years before your cover starts, though the period varies by insurer). After you’ve been symptom-free for a certain period of time (usually two years), your insurer will usually reinstate cover for that particular condition or illness.
However, every time you claim, your insurer will look at your medical history and determine whether or not your claim is valid. In some instances, your insurer will ask to speak to your GP or other health professional for clarification.
Moratorium underwriting can mean your claim takes longer to process.
- Find out more in our guide to moratorium underwriting
Full medical underwriting
Instead of waiting until you make a claim, insurers will ask you to fill in a comprehensive health questionnaire before they issue a policy. Insurers may also ask your permission to speak to your GP or other health professional. You’ll also be asked about any pre-existing conditions when you apply.
This information means insurers can tailor a specific policy based on your medical history. Your policy documents will then clearly set out what illnesses aren’t covered.
Because your insurer already has all your medical details and a greater understanding of your health, claims are usually quicker to process than moratorium policies. The price can differ between the two methods depending on the insurer, so it’s worth comparing quotes on both.
- Find out more in our guide to full medical underwriting
Why are health insurance premiums so expensive?
Your premiums help pay for private medical treatment (alongside what other policyholders pay). Of course, thanks to the NHS, most of us don’t actually realise just how expensive even common medical procedures really are.
To put this into perspective, here are some common surgical procedures and how much they cost to carry out in a private hospital, from our 2024 research:
- Knee replacement £15,138
- Hip replacement £14,412
- Tonsillectomy £3,130
- Wisdom teeth extraction £2,563
- Colonoscopy £2,421
- Carpal tunnel release £2,427
Also, bear in mind that premiums will be affected by costs outside of insurers’ control, such as rising energy prices.
But on top of everyday price rises, healthcare is also affected by medical inflation. This is the price of healthcare treatments themselves, including new drugs and investing in newer technology.
Will my health insurance premiums increase every year?
Health insurance premiums are more likely to rise rather than fall, and most people will experience premium increases at renewal.
That said, the amount by which they increase will depend. They won’t necessarily always increase by the same amount each year. Premiums will be affected by your circumstances (such as your age, health and claims) and by external factors (for example, general and medical inflation).

What does private health insurance actually cover?
Private health insurance covers acute conditions. These are illnesses and conditions that get better or can be cured with treatment, for example, cataracts.
While policies will vary according to your level of cover, you can expect most plans to provide:
- GP access 24/7, usually by phone or video call
- Inpatient treatment (where you stay in hospital overnight)
- Day-patient treatment (if you need to stay in hospital for several hours but not overnight)
- Post-surgery or treatment tests, including consultant appointments
- Cancer treatment
Some policies also include added benefits such as an NHS cash benefit, which means you’ll get money back if you choose to have NHS treatment instead of private.
Watch: How private health insurance works
Here's a short video explaining how private health insurance works:
What isn’t covered by private health insurance?
Private health insurance doesn’t cover chronic conditions. These are illnesses and conditions that cannot currently be cured, for example, diabetes. Policies also won’t usually cover pre-existing conditions: on moratorium cover, a condition can be covered again once you’ve gone two years in a row without symptoms, treatment or advice for it, while full medical underwriting can exclude it for good.
Is private health insurance worth the money?
In the UK, we’re lucky enough not to need private health insurance. Nevertheless, in practice, NHS waiting lists can be a barrier to accessing timely treatment, which is a genuine concern for many of us.
Private health insurance can be a way to avoid waiting lists, as well as providing you with other benefits that can help you maintain your health, both physically and emotionally.
Policies don’t need to be expensive either, because basic private health insurance typically covers GP access and inpatient and day-patient hospital treatment for new conditions, as well as follow-ups after surgery.
If you’re weighing up the pros and cons and need more clarity on what’s covered, these in-depth guides may help:
- Is private health insurance worth it?
- 12 tips when buying health insurance
- What’s the difference between comprehensive and basic health insurance plans?
- Self-pay versus private health insurance
“Clear and concise information”
Clear and concise information. Very helpful in helping us find an affordable health insurance premium for our family
How can I keep health insurance premiums down?
You can keep health insurance premiums as low as possible by:
- Choosing your policy carefully – the more features there are, the more you can expect to pay, but limiting additional therapies such as acupuncture and physiotherapy can help keep premiums down.
- Limiting your hospital network – if you know you’ll only want to be treated close to home, stick to a regional hospital network instead of paying for an expensive national list.
- Opting for a restricted consultant list – your provider will always ensure you see a specialist for the health condition you’re suffering from. If you don’t mind who that is, limiting the consultant list can result in premium savings.
- Staying healthy – recent claims can lower your no-claims discount, but staying healthy can help you qualify for the good-health discounts some insurers offer, and Aviva's My Healthy Discount rewards healthy actions during the year with up to 15% off your renewal premium.
- Increasing your excess – when you claim, you’ll normally be asked to pay an excess. Increasing this amount can reduce your overall premium (but it should still be affordable).
Want to know more ways to lower your premiums? Our guide to reducing health insurance premiums covers even more options, including how much money each one could save you.
Read next
See 2026 prices by age, check if you can switch without new exclusions and compare leading UK insurers.
Tailoring private health insurance to your needs
Private health insurance is an investment in your wellbeing. Any plan you choose should give you peace of mind, knowing that you can get the help and treatment you need when you need it most.
To explore your options, contact us and we’ll put you in touch with one of our FCA-regulated partner brokers, who we vet and monitor.


More questions? Search our site to find the answers
Disclaimer: This is general information, not personal advice. Speak to a qualified broker before making a decision. Our broker partners compare policies from a panel of leading UK health insurers, but not all insurers may be available.