


How claiming on your private health insurance can affect your discount and what you pay
In this guide, we’ll break down how claiming on your private health insurance policy can affect your no claims discount and what you pay in the future. We’ll compare the models of six leading insurers and try to cut through some of the complexities to provide you with clear, actionable insights.


Richard Eagling is the Senior Editor at myTribe, with 25+ years in personal finance journalism and a CII Certificate in Financial Services. Previously at Moneyfacts and NerdWallet UK, his work has featured in The Guardian, BBC and The Telegraph.
Full BioUnderstanding your health insurance no claims discount
Here’s a quick overview of the main things you need to consider about no claims discounts (NCDs) on health insurance policies:
- NCDs in private health insurance policies work differently to other types of insurance, such as motor insurance.
- With most private health insurers, you’ll start with a relatively high discount and move up or down a sliding scale depending on how much you claim.
- Each insurer has its own rules; with variations in the starting discount, the maximum discount, and the claim amount allowed before your NCD is reduced.
- If you don’t make a claim and move up your insurer’s NCD scale, your next renewal price will usually be lower than if you had claimed.
- Pounds and pence savings matter more than percentage discounts: compare the actual costs, not just the percentages.
What is a no claims discount, and how does it work in the UK?
If you’re a driver, you’re probably already familiar with no claims discounts (NCDs). They reward you for not making a claim on your insurance. The longer you go without claiming, often, the bigger the discount.
With car insurance, you start with no discount and build it up over time. Every year you have insurance without making a claim, the discount gets bigger – up to a maximum set by your insurer.
Many private health insurance policies also offer NCDs. They work differently, but the effect of making claims is similar – your policy will usually cost more at renewal than if you hadn’t.
Cert CII (IF1, IF7, I10)
What our expert says
Unlike car insurance no claims discounts, where there’s little to lose in the early years but plenty to gain over time, a private medical insurance no claims discount works almost in reverse, with more to lose than to gain.
The overall effect is that a no claims discount in private health insurance acts more like a penalty for claiming than a reward for not. That’s why it’s important to understand how your own no claims discount works and to compare it against what other insurers offer.
How do health insurance no claims discounts work?
When you get a new private health insurance policy from a provider that offers an NCD, you’ll usually start from day one with a significant discount of up to 70% off the base premium. This is the starkest difference to motor insurance, where you start at 0% and work your way up.
This means health insurance claims can have a big impact on the policy price at renewal, particularly in the early years.

What is an insurance “base premium”?
Your base premium is the full price of your insurance before any no claims discount is applied. So, if you have a 70% discount, and your renewal quote is £100 per month, the actual underlying cost of the policy is £333.33 per month (£100 ÷ 0.30).
While your renewal documents may not show it, calculating your base premium is useful, as it will allow you to see better how a claim and a reduction in your discount percentage may affect your next renewal.
Use our base premium calculator to find out the underlying cost of your insurance (this can be used for any insurance with a no claims discount).
How each UK health insurer’s no claims discount works
We’ve captured screenshots of each of the UK’s leading health insurance providers’ no claims discount scales and terms, so you can quickly browse them all. Select an insurer to view their discount, and check below the image for their key rules.
Aviva
What is the NCD scale for Aviva health insurance?
Aviva's Healthier Solutions uses a 15-level scale starting at level 12 (69% discount). The scale runs from level 0 (0%) to level 14 (75% maximum discount).

How does Aviva's no claims discount work?
- Eligible claims of £250 or below (after excess) have no impact.
- Claims over £250 drop you 3 levels – harsher than most insurers.
- Each person has their own NCD – one person's claims don't affect others' discounts.
- Example: A £500 eligible claim drops you from level 12 (69%) to level 9 (59%).
- Exempt claims: NHS cash benefits, dental, optical, and therapies.
AXA Health
What is the NCD scale for AXA Health?
The AXA Health Plan has 16 levels, and new customers on a moratorium start at level 13. The top level gives a 75% maximum discount, but AXA Health has not published the discount for each level.
How does AXA Health's no claims discount work?
- Total claims paid of less than £250 in a year make no difference. £250 or more drops you 1 level, £500 or more drops you 2 levels and £1,000 or more drops you 3 levels.
- AXA Health does not say whether each person has their own NCD or whether it is shared across the plan.
- Example: A £500 claim drops you from level 13 to level 11.
- Exempt claims: Cash benefits (including if you choose to have your treatment on the NHS), Doctor at Hand consultations, dental and optical cashback, external prosthesis, hotel accommodation and hospice donations.
Bupa
What is the NCD scale for Bupa health insurance?
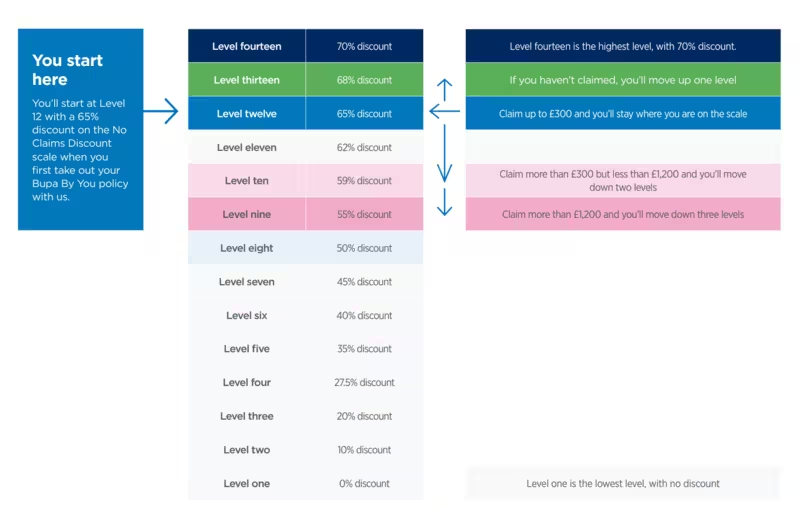
Bupa By You uses a 14-level scale starting at level 12 (65% discount). The scale runs from level 1 (0%) to level 14 (70% maximum discount).
How does Bupa's no claims discount work?
- Eligible claims up to £300 (after excess) have no impact.
- Claims £300–£1,200 drop 2 levels.
- Claims over £1,200 drop 3 levels.
- Each person has their own NCD – one person's claims don't affect others' discounts.
- Example: An £800 eligible claim drops you from level 12 (65%) to level 10 (59%).
- Exempt claims: Dental Cover Add-on, NHS Cash Benefit, Anytime HealthLine, and Digital GP consultations.
Saga
What is the NCD scale for Saga's health insurance?
Saga's HealthPlan uses an 11-level scale starting at level 5 (35% discount). The scale runs from level 0 (0%) to level 10 (60% maximum discount).

How does Saga's no claims discount work?
- Drops 2 levels for each separate medical condition claimed (after excess), regardless of amount – uniquely harsh for multiple conditions.
- Single NCD for the entire policy – any family member's claim affects everyone's discount.
- Example: Starting at level 5 (35%), three claims for different conditions drop you to level 0 (no discount).
- Exempt claims: NHS cash benefit, physiotherapy/acupuncture, Mental Health Direct Access, Saga GP Service, and dental cash benefits.
The Exeter
What is the NCD scale for The Exeter's health insurance?
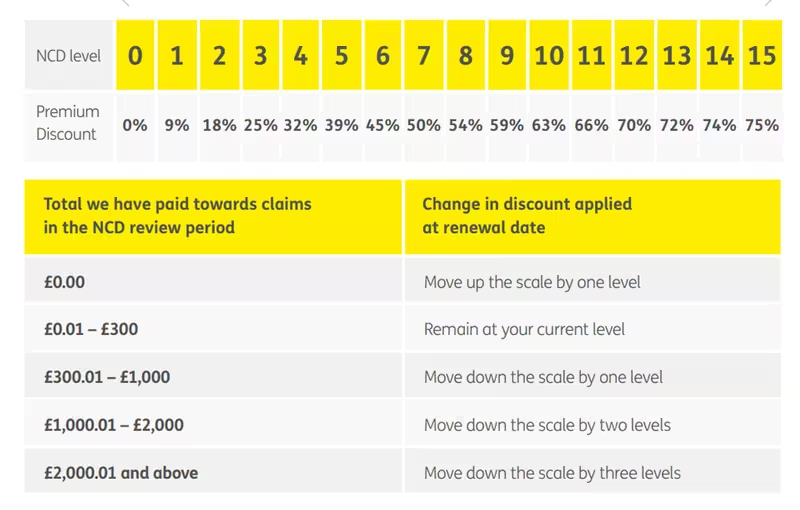
The Exeter's Health+ uses a 16-level scale starting at level 12 (70% discount). The scale runs from level 0 (0%) to level 15 (75% maximum discount).
How does The Exeter's no claims discount work?
- Most lenient thresholds:
- Claims up to £300 (after excess) – no impact.
- Claims £300–£1,000 drop 1 level.
- Claims £1,000–£2,000 drop 2 levels.
- Claims over £2,000 drop 3 levels.
- Each person has their own NCD, with protection for ongoing treatment across review periods.
- Example: A £750 eligible claim drops you from level 12 (70%) to level 11 (66%) – the smallest drop among major insurers.
- Exempt claims: NHS cash benefit, hospice donations, and any claim below your excess.
WPA
What is the NCD scale for WPA's health insurance?
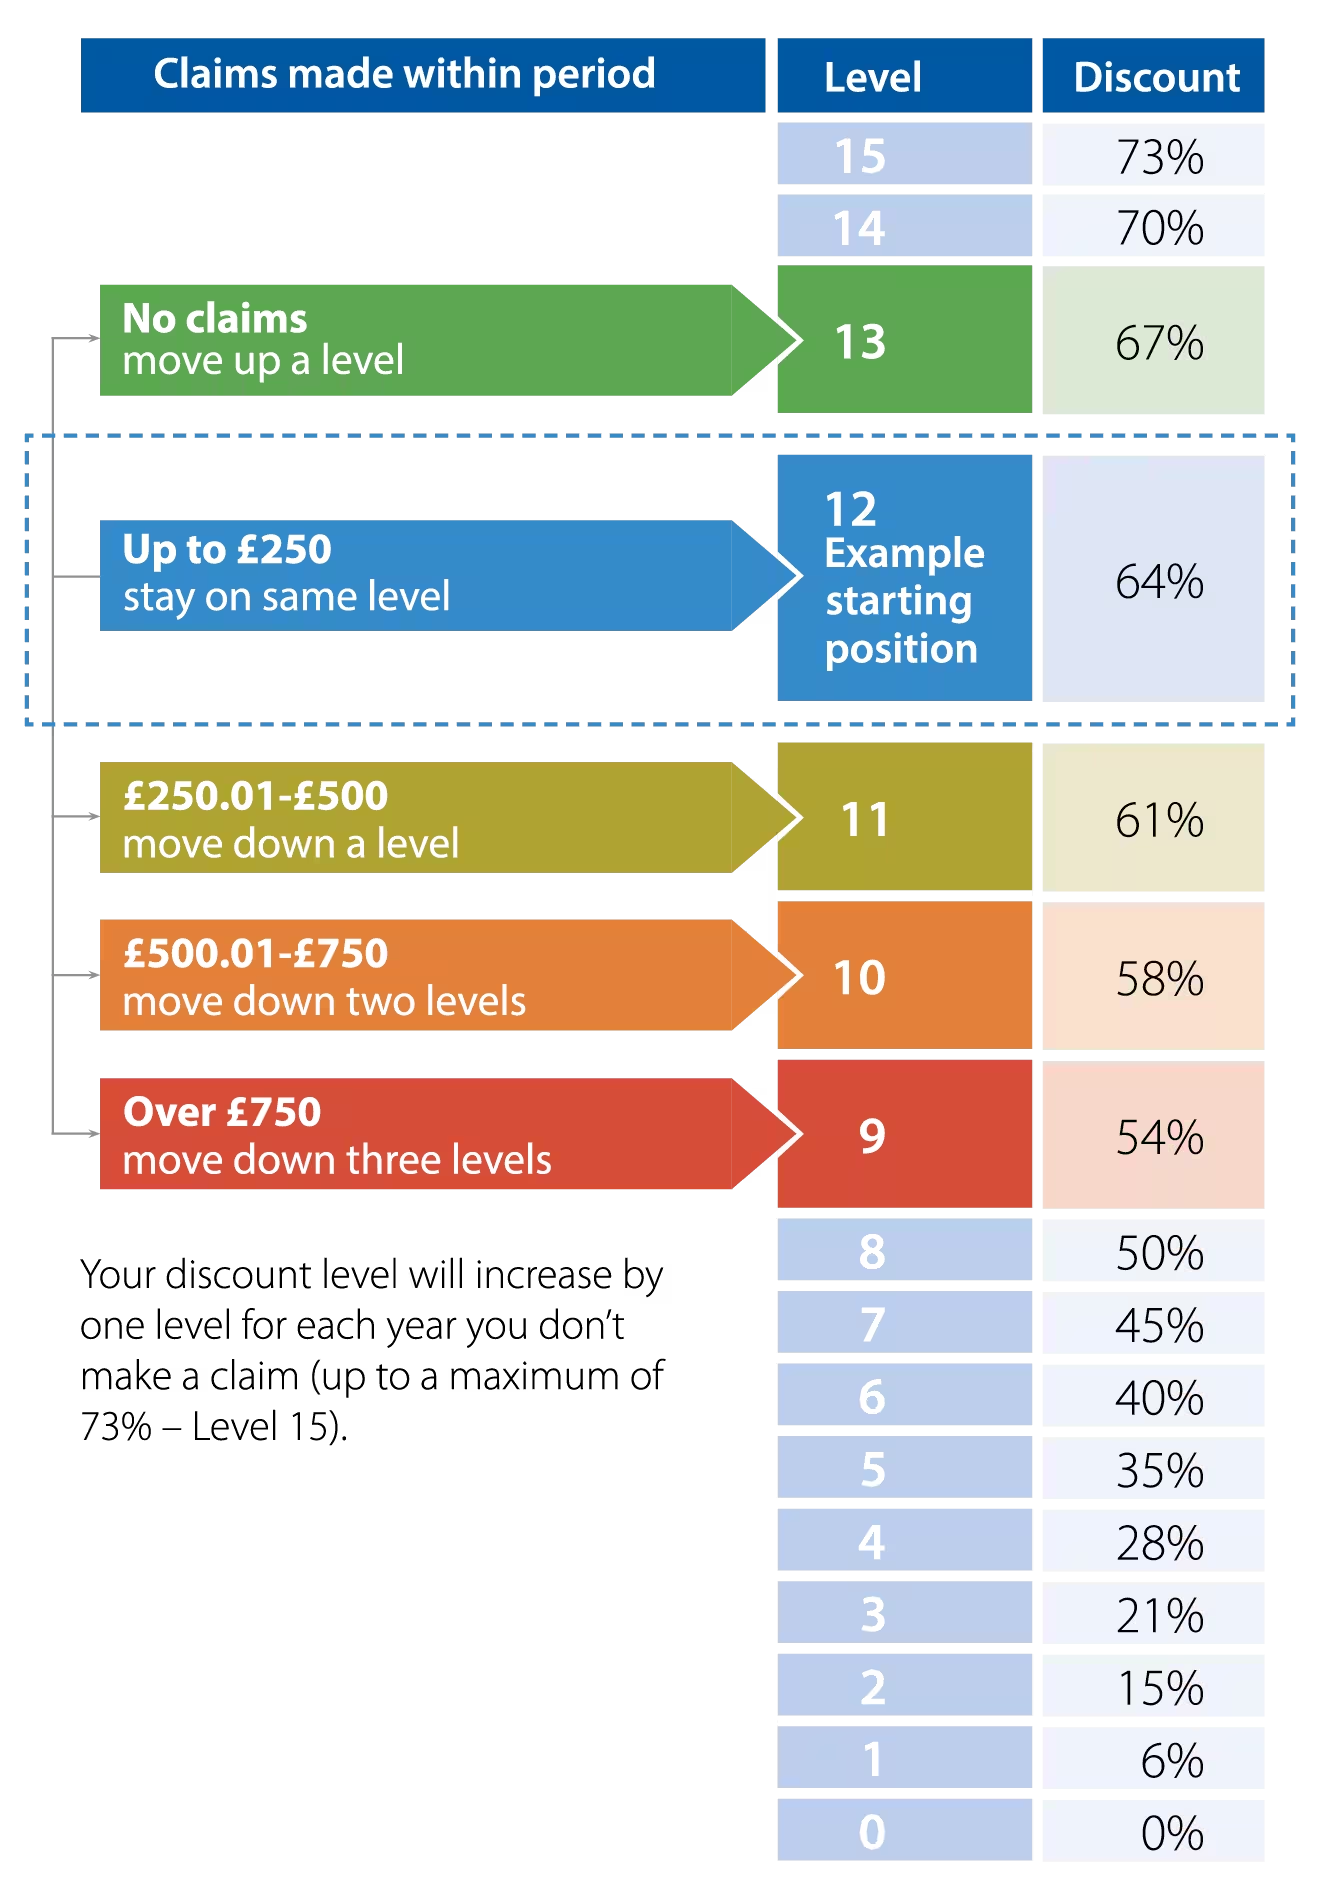
WPA's Complete Health uses a 16-level scale starting at level 12 (64% discount). The scale runs from level 0 (0%) to level 15 (73% maximum discount).
How does WPA's no claims discount work?
- Eligible claims up to £250 (after excess) don't affect your discount level.
- Claims £250.01–£500 drop 1 level.
- Claims £500.01–£750 drop 2 levels.
- Claims over £750 drop 3 levels.
- Each person has their own NCD – one person's claims don't affect others' discounts.
- Example: A £400 eligible claim drops you from level 12 (64%) to level 11 (61%), while a £900 claim drops you to level 9 (54%).
- Exempt claims: Health and Wellbeing benefits, NHS Hospital Cash Benefit, Physio Pathway, Fast Track Skin Support Pathway, Cash Extras, hospice donations, and Dental Emergencies.
Pretty confusing, right?
As you can see, there’s significant variation across insurers: different levels, starting points, percentages and rules. Let’s break this down to make it easier to compare.
Comparison of health insurer NCD starting levels
Most private medical insurance plans start around the top of their no claims discount scale, often around level 12 of a possible 14-16 levels.
- No claims in a policy year: You typically move up one level, increasing your discount slightly.
- Making a claim: You may drop multiple levels in one year, depending on the claim size and insurer’s rules.
As you can see from the table, Saga is an exception, as it starts most new policies midway through its discount scale at level five. Although both the starting and maximum discounts are lower than other providers, it doesn’t mean that Saga’s NCD is better. It penalises claims more heavily and the NCD is per policy, not person (more on that later).

Will your medical insurance get cheaper if you don’t make a claim?
It’s very unlikely your health insurance renewal quote will be lower, even if you don’t make a claim. There are many things that affect the cost of a health insurance policy. For example, age. As we get older, we’re more likely to suffer from health problems and more likely to make a claim on our insurance.
Providers will factor this into their pricing – along with other factors, including medical inflation – when they give you a renewal quote. The cost of your insurance won’t necessarily go down if you don’t make a claim, but it will be cheaper than if you had.
Compare health insurance before your next renewal
Compare health insurance from leading UK insurers and see what cover would cost you at your age.
Compare health quotesClaim impact on health insurance discounts
It’s not very simple to compare UK health insurance providers’ NCDs because they use different scales. Some have more levels than others, and the percentage discounts associated with each level aren’t always the same.
Something all of those that offer an NCD have in common though is that the amount of discount offered between levels gets larger the further down the scale you fall. In other words, you lose a larger percentage of your NCD the more you claim.
How claims of different sizes affect your NCD
Although it’s not easy to compare providers directly, one difference between them is how NCDs are affected by smaller claims.
Expert insight
As you can see from the table, some private health insurance providers are more lenient when it comes to smaller claims.
The Exeter, for example, won’t change your no claims discount level until claims reach £300, and you won’t move down three levels until they reach £2,000. AXA Health’s Health Plan, on the other hand, moves you down one level at £250 and three levels from £1,000.
This isn’t an exact comparison, because the percentage discounts associated with the levels differ. And even the percentages aren’t as important as the pounds and pence figures behind them. But it’s still useful as a guide for how providers treat smaller claims differently.
Saga does things quite differently from the rest
One major provider we haven’t included in the above table is Saga. This is because it doesn’t assess claims based on the total cost in a policy year. Instead, Saga will move you down two levels for each condition you claim for (treatment for the same condition within 12 months counts as one claim). So if you make multiple claims in a single policy year, you could lose your NCD much more quickly.
Another key difference with Saga is that its NCD is per policy, not per person as it is with Aviva, Bupa, The Exeter and WPA. This means all claims have the same impact on the NCD, no matter who makes them.
How Saga’s policy-wide NCD compares to other insurers’ per-person approach
If you consider a family policy with two adults in their 50s and two teenage children, we’d expect 80-90% of the cost of the policy to be due to the adults on the plan.
With Aviva, Bupa, The Exeter or WPA, each family member would have an NCD, so if a child claimed and their discount was affected, or even fully lost, it likely wouldn’t have a huge impact on the overall cost.
By contrast, Saga’s approach of a shared NCD would result in a very different outcome, as the child’s claims would affect the “shared” discount, likely resulting in a significant price rise. If you’re covering your family, compare plans where each person has their own discount before you decide.
Do all health insurance providers offer a no claims discount?
Most private health insurance providers in the UK offer NCDs in some form, but not all of them use a sliding scale. Vitality, for example, uses its own “ABC” model:
- Age
- Base inflation
- Claims
So despite not using a sliding scale, claims are still an important factor that will affect the cost of your policy at renewal.
Some, like Freedom Health Insurance, do not offer an NCD at all, although it’s likely that your claims history will still be a factor in your renewal price.

Not sure which no claims approach suits you?
Insurers handle claims in very different ways. Compare health plans from leading UK insurers and see what each would cost you.
Rated Excellent

on
Types of claims that won’t affect your no claims discount
Some claims won’t affect your NCD at all. This varies between providers, but generally the following types of claims won’t see you move down any levels on the NCD scale:
- Cash benefits (e.g. dental, optical and NHS)
- Remote GP consultations
- Helplines and support services
Another thing to note is that any claims you make below your excess amount won’t affect your NCD. This is because your insurer won’t need to pay out unless your claim exceeds your excess.
Your excess and how it affects your no claims discount
Your excess is the amount you have to contribute towards a claim. For example, if you choose a £500 excess and the cost of your treatment is £2,000, you’ll pay £500 and your insurer will pay the rest.
Most insurers let you choose your own excess, and it’s directly related to the cost of your policy. If you choose a higher excess, you will pay a lower price for your cover.
This is important because any claim you make under the excess amount won’t affect your NCD. Setting a higher excess may make you shoulder more of the initial cost, but it could save you money in the long run. The right choice for you will be an individual one, but it’s worth considering when choosing the excess for your policy.
Related articles
- How to reduce the cost of your private health insurance (14 ways ranked by savings)
14 ways to lower your premium, ranked by savings, including what a £250 or £500 excess saves and when paying a small bill yourself protects your discount.
- How to get the best deal on your health insurance renewal
When your no claims discount for next year is worked out, why most premiums rise at renewal, and five ways to get a better deal.
- How to get affordable health insurance
See what new customers pay at your age, compare it with your renewal and check whether you could switch for less.
Protecting your no claims discount
Some insurers will give you the option of protecting your NCD. This means you’ll pay a bit more for your insurance, but won’t lose your discount if you make a claim. Insurers such as Aviva and The Exeter offer a paid option to protect your no claims discount, and AXA Health may offer one in some cases for a small fee, so ask your insurer what it can add.
If you claim on your health insurance while your NCD is protected, you’ll lose the protection for a period, usually one or two years. If you don’t make another claim in that time, you’ll be able to add NCD protection again.
What you need to consider about private health insurance no claims discounts
Most health insurance providers offer NCDs in one form or another, but they don’t work in the same way as motor insurance NCDs. Many of them use sliding scales, which means you have more to lose than gain.
Variations in how these scales work make comparing providers difficult. The differences largely come from how much you can claim before you move down the scale and how far down you move.
Providers that allow small claims without affecting your NCD may offer more protection. But if you claim consistently and for large amounts, you’ll end up at the bottom of the scale, no matter who your insurer is.
Levels and percentages aren’t as important as the pounds and pence figures behind them. The higher the base premium, the more it will be affected by dropping down levels on the NCD scale.
Your excess can have a big impact on your NCD. A higher excess may make treatment more expensive, but it could save you money in the long run. It will also reduce your premium. In some cases, it may even save you money to pay for treatment yourself.
Compare health insurance costs, not just discounts
Compare the UK’s leading health insurance providers and join thousands who have found the right cover with myTribe.
Rated Excellent
on
Frequently Asked Questions
Does claiming on health insurance affect how much it costs?
Usually, yes, although how much difference it makes will depend on who your insurer is and the value of your claim. Some types of claims won't affect the cost of your policy at all.
Which health insurer offers the best no claims discount?
This depends on several factors, including the cost of the policy in pounds and pence and the frequency of your claims. But The Exeter and Bupa have some of the most lenient rules for smaller claims. Some providers offer a higher initial percentage discount, but this may drop relatively quickly compared to others. Some insurers offer lower initial discounts but don't penalise you as heavily for smaller claims.
Does a policy excess protect my no claims discount?
Partly, because a higher excess means more claims fall below it: if the cost of treatment is lower than your excess, you won't lose any of your discount, as the insurer doesn't have to pay out. So choosing a higher excess can protect your NCD as well as keeping down the cost of the policy. Some insurers will also allow you to pay for medical treatment yourself to avoid losing your NCD.
Does Vitality offer a no claims discount?
Vitality doesn't offer a traditional no claims discount with a sliding scale. It uses its own “ABC” model to set its prices. Claims are still a factor in this and will affect your renewal price.
How does the AXA Health Plan no claims discount work?
The AXA Health Plan has 16 levels, and new customers on a moratorium start at level 13. Claims paid under £250 in a year make no difference, while larger claims move you down one, two or three levels depending on the total. AXA Health has not released the percentage discounts for each level, so it is difficult to compare directly with other insurers.


More questions? Search our site to find the answers
Disclaimer: This is general information, not personal advice. Speak to a qualified broker before making a decision. Our broker partners compare policies from a panel of leading UK insurers, but not all insurers may be available.