


Does private health insurance cover complementary and alternative therapies?
An essential part of private health insurance is to provide cover for acute conditions that can be effectively treated in hospital. On top of that, insurers may also offer you a range of additional benefits, either as standard or as an optional extra. Here, we look at complementary and alternative treatments and whether they’re included in private health insurance policies.


Richard Eagling is the Senior Editor at myTribe, with 25+ years in personal finance journalism and a CII Certificate in Financial Services. Previously at Moneyfacts and NerdWallet UK, his work has featured in The Guardian, BBC and The Telegraph.
Full BioWhat are complementary and alternative therapies?
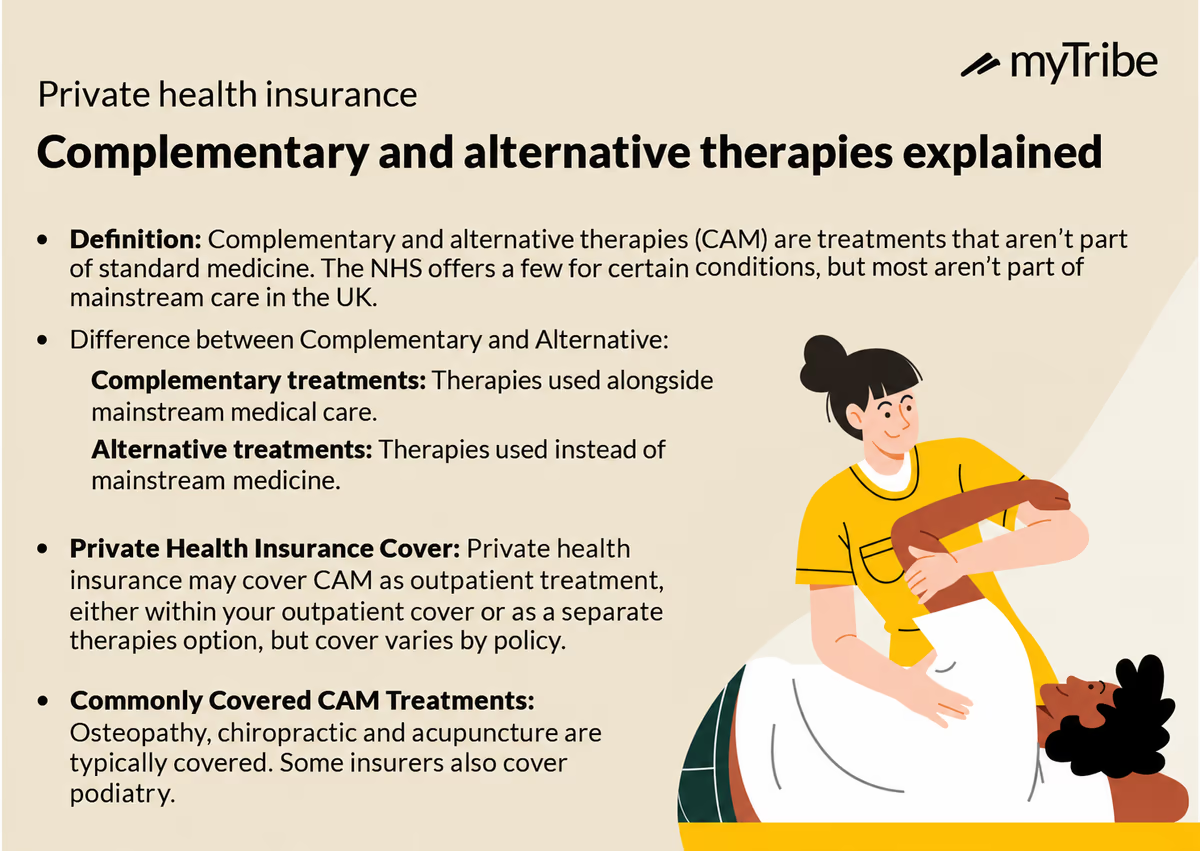
Complementary and alternative medicine (shortened to CAM) covers treatments that aren’t part of standard medicine. The NHS may offer a few of them for certain conditions, such as acupuncture for long-term pain, but most aren’t provided as part of mainstream care in the UK.

What’s the difference between complementary and alternative treatments?
Complementary treatments are used alongside mainstream medical care, while alternative treatments are used instead of it.
- Complementary treatments are therapies that are used alongside any other mainstream care.
- Alternative treatments are therapies used instead of mainstream medicine.
With that in mind, there may be overlap between the two. For example, if you have joint pain, your GP may recommend steroid injections or painkillers. If you choose to have acupuncture in addition to this, it would be considered a complementary treatment. However, if you decided just to have acupuncture and avoid steroids and painkillers, it could be viewed as an alternative therapy.
Examples of complementary and alternative medicines in the UK
CAM covers a broad range of treatments, including:
- Acupuncture – very fine needles are put into specific areas of your body (acupuncture points) to relieve pain.
- Osteopathy – this involves stretching, massaging and moving your body to improve mobility, muscle tension and circulation.
- Homeopathy – very watered-down mixtures made from plants, animals or minerals are used to try to treat symptoms.
- Chiropractic – the relief of joint pain (such as neck, back, elbow, and shoulder) through manipulation of muscles, bones and joints.
- Podiatry – podiatrists diagnose and treat foot conditions. They’re regulated health professionals, and some insurers include podiatry in their therapies cover.
These are just a handful of common examples, but CAM can also cover therapies such as aromatherapy, craniosacral therapy, and Reiki.
Does private health insurance cover complementary and alternative medicine?
Private health insurance can include complementary and alternative therapies as outpatient treatment, either within your outpatient cover or as a separate therapies option, but this will depend on the policy you choose.
Some policies may include certain complementary and alternative therapies as standard, or it could be a feature you can pay to add. For example, Bupa and Saga include osteopathy, chiropractic and acupuncture in their outpatient benefits, while Vitality and The Exeter only cover them if you add a therapies option.
Be aware that there may also be limits to how much you can claim towards treatment. This could be restricted to a fixed number of sessions, such as up to 10 a year for each condition with Aviva, or a value, from £250 a year on most General & Medical plans to £1,500 a year with WPA. Some policies offer an unlimited number of sessions or value, but this is likely to be reflected in higher premiums.
Your insurer may also only pay out for certain types of CAM. For instance, chiropractic treatment is widely covered, but only a few insurers, such as Vitality, WPA and Freedom, cover homeopathy. Check your policy documents before booking Reiki or aromatherapy.

Our expert guide to the best private health insurance in the UK. Find out which insurers have the best reviews and cover levels.
What CAM does private health insurance usually cover?
The CAM treatments covered depend on your health insurance policy, which sets out the therapies it will pay for.
Popular treatments that are typically included are osteopathy, chiropractic and acupuncture. Some insurers, such as Bupa, Vitality and The Exeter, also cover podiatry, but others, such as Saga and General & Medical, don’t.
Which practitioners can I use with health insurance?
Your insurer may specify which practitioners it will pay for, so check your policy documents before booking treatment. Usually, if the treatment is recognised and has a regulatory body, you would be expected to see a practitioner who is either licensed or has regulatory approval. A good example is chiropractic treatment, where chiropractors must be registered with the General Chiropractic Council in order to practise. Most insurers also only pay practitioners they recognise, so check with yours before you book.

Find the best health insurance for you!
Compare the UK’s leading health insurance providers and get expert advice from an experienced insurance specialist.
Rated Excellent

on
Are complementary and alternative therapies beneficial?
Complementary and alternative treatment can be beneficial. However, where a particular treatment works for one person, it may or may not have the same effect on you.
Complementary treatments that run alongside mainstream medicine can also provide you with a more holistic approach to your overall care.
Remember that CAM is considered outside of the mainstream because there may not be enough scientific data to show how effective it is. This doesn’t mean it won’t work for you, but it does mean you should research what’s available and who to see.
Before you have any treatment, you should consider:
1. Check how CAM could affect your existing treatment
If you’re being treated for something with mainstream medicine, consider how CAM might affect this. Not all alternative therapies will be compatible, and some may interfere with the treatment you’re already having.
It’s important to speak to your GP, nurse or other healthcare professional before having any other treatments. You should also let your CAM practitioner know about any mainstream care you’re having.
2. Check your CAM practitioner’s registration
If you’re having treatment that is regulated, ensure that your practitioner is registered: chiropractors and osteopaths must be registered by law. For other therapies, the NHS suggests choosing a practitioner who’s on a register accredited by the Professional Standards Authority. At the very least, practitioners should have appropriate qualifications.
If you’re not sure where to look, your GP may be able to help or recommend someone.
If the treatment you’re interested in isn’t regulated, check reviews on independent sites and don’t be afraid to ask questions if you’re unclear about anything. Professional and qualified practitioners will be used to this and shouldn’t mind giving you the information you need.
3. Ask about the side effects of CAM
You can have side effects with almost all treatments – mainstream or otherwise. Before you have any sort of treatment, you should be told what the potential side effects could be.
If your symptoms don’t go away or keep coming back, ask a GP for advice rather than just talking to your therapist. If you experience any negative side effects, always let your practitioner know straight away.
Remember – speak to your GP or consultant before you have any treatment.
Health insurance insights you can trust!
We’re the UK’s trusted insurance and healthcare resource, rated ‘Excellent’ on Google Reviews.
“Clear and concise information. Very helpful in helping us find an affordable health insurance premium for our family”
Joey Mort
Rated Excellent 5/5 on Google Review

“I would recommend using this service to anybody in need of insurance option comparisons. Fast, friendly and very efficient, individualised service.”
Jeannie Cherry
Rated Excellent 5/5 on Google Review
Should I add CAM to my private health insurance?
Whether to add CAM cover depends on the therapies you want to use, what your policy already covers and any extra premium. Most private health insurers offer some sort of complementary or alternative therapy, although you may have to pay extra for it.
Despite a lack of conclusive evidence, people often use complementary therapies to help them feel better and cope with an illness such as cancer and its treatment.
If you want to find out more about private health insurance and what it can offer you, we can put you in touch with one of our FCA-regulated partner brokers, who we vet and monitor.
To give you a better idea of how private health insurance works, we’ve also put together these in-depth guides:
Frequently Asked Questions
Should I use alternative therapies?
Many people do find complementary and alternative therapies beneficial, whether to complement mainstream medical treatment or just for relaxation and their wellbeing.
That said, it’s a personal choice, and there’s no guarantee that you’ll experience the same benefits as someone else. Not every therapy is safe or suitable for everyone, so tell your GP and your therapist about any medical conditions you have and any medicines you take.
How do I find alternative and complementary treatments?
Recommendations from your GP, other health professional, or friends and family are a good starting point. Otherwise, check review sites rather than simply relying on practitioners’ websites.
Don’t forget to check if the therapy you’re interested in is regulated. Chiropractors and osteopaths must be registered by law; for other therapies, look for a practitioner on a register accredited by the Professional Standards Authority.
When you find a practitioner, it’s worth making sure you’re clear about:
- What their qualifications are.
- How much they charge.
- How long until you can expect to see or feel results.
- Whether there are any side effects.
- What the complaints process is and what insurance they have.
- Whether there is anything that might prevent you from having treatment.


More questions? Search our site to find the answers
Disclaimer: This is general information, not personal advice. Speak to a qualified broker before making a decision. Our broker partners compare policies from a panel of leading UK health insurers, but not all insurers may be available.